Reported by
A U.S. federal grand jury has indicted the founder and sole owner of crypto startup Few and Far, on securities and wire fraud charges over an alleged scheme to divert millions of dollars raised from investors to online gambling and personal expenses.
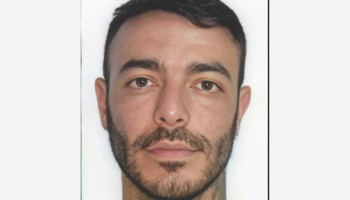
Taj Tarsha, 34, of Miami, was arrested June 6, and his case has been assigned to U.S. District Judge Lewis A. Kaplan, the U.S. Attorney’s Office for the Southern District of New York said. Each count carries a maximum sentence of 20 years in prison if he is convicted.
Few and Far told investors it was developing a decentralized marketplace for non-fungible tokens, or NFTs. Beginning in February 2022, prosecutors say, Tarsha solicited investments through Simple Agreements for Future Tokens, under which investors paid upfront for the right to receive the startup’s FAR tokens at a later date. Offering documents said the money would be used to develop both the marketplace and the token.
Tarsha allegedly raised more than $10 million from at least 67 investors by selling rights to 95 million FAR tokens, according to the indictment. Few and Far publicly announced in March 2023 that it had raised $10.5 million in a round led by blockchain investment firm Pantera Capital and joined by several other venture capital firms. The indictment does not identify the defrauded investors.
Prosecutors allege Tarsha began diverting money almost immediately, using investor funds to gamble at an online casino and buy speculative cryptocurrencies. He also allegedly siphoned off nearly $1 million as compensation through two bonuses concealed from investors and a co-founder, along with a salary he acknowledged was unreasonable because Few and Far had no product and “zero revenue.”
A June 2023 audit uncovered the spending, prosecutors said. Tarsha allegedly told investors that the bonuses were tied to predetermined token presale targets and that all transactions had benefited the company. But by then, according to prosecutors, he had fired almost all staff and instructed the remaining contractor to perform work intended to create the appearance that development was continuing.
For at least another year, Tarsha allegedly spent investor money on cryptocurrency purchases, a Miami condominium loan, interior design services and his DJ hobby. The FAR token launched in May 2024 but was effectively worthless and soon stopped trading, prosecutors said.
Tarsha’s lawyers, however, argued he “never intended to defraud anyone,” stressing that “sophisticated investors knowingly invested in digital assets back in 2022 at a time of extraordinary optimism, understanding both the risks and the potential rewards.”
“We are disappointed that the government has chosen to pursue criminal charges against the founder of a legitimate Web3 startup that built a real NFT marketplace, launched its token, and then confronted the same market collapse that devastated countless other NFT projects,” Kaela Dahan and Evan T. Barr of Reed Smith LLP, told OCCRP.
They said prosecutors are relying on hindsight and “selective storytelling” to rewrite a failed business venture as a criminal fraud case.
“But business failure is not a crime,” the attorneys added. “Mr. Tarsha is innocent and looks forward to being fully exonerated.”